In an alternate universe in which I run a high-end grocery store, this Salmon Salad is a customer favorite. Tender baked salmon that's flaked, then tossed in a creamy, herby Greek yogurt dressing, it strikes the ideal balance between casual and fancy.
As an adult, chunky, protein-packed salads have moved from restaurant to refrigerator.
I always feel better about the week ahead when I've taken time to make myself a batch of Italian Tuna Salad or Chickpea Tuna Salad and stash it in the fridge.
They're healthy, keep me full, and make lunch something to look forward to, instead of a weekday drag.
After cooking a particularly large batch of Baked Salmon in Foil, I found myself with a hefty amount of leftover salmon and craving something new for lunch.
Enter, Salmon Salad!
This recipe takes the principle of tuna salad and chicken salad—lean protein meets creamy dressing meets all kinds of yummy, crunchy bits to liven things up—but swaps in flaked salmon, instead of tuna or chicken.
With as often as we eat fresh salmon fillets as a main (sometimes twice a week as this list of salmon recipes can attest) and use canned salmon to make the Salmon Quinoa Cakes in my cookbook, plus the fact that chicken salad and I go all the way back to childhood, I don’t know why it took me this long to make a creamy salad with salmon. I'm here for it now!
How to Make Salmon Salad
This salmon salad draws inspiration from a combo of classic Waldorf salad ingredients such as dill and nuts, with a touch of Mediterranean flair.
It's creamy, crunchy, filling, and fresh. You'll love having it in your refrigerator too!
The Ingredients
Salmon. A fantastic source of protein, high in essential Omega-3s which help your heart and brain, and superbly scrumptious, salmon is a great “gateway” fish. For the best results and max health benefits, look for wild caught.
Substitution Tip!
As much as I appreciate canned salmon and tuna for their budget-friendly, healthy prowess (that's why I use it to make this Salmon Patty recipe and these Avocado Tuna Cakes), for this salmon salad recipe, I strongly suggest using fresh salmon. As with these Salmon Burgers, using fresh salmon is important for creating the proper texture. The salmon is tender and satisfying, without making the salad mushy.
You could also try mixing up a smoked salmon salad, by swapping the baked salmon for diced smoked salmon.
In the summer, instead of baking the salmon, fire up the grill and make a grilled salmon salad. (This Grilled Salmon in Foil will show you how.)
Greek Yogurt. This healthy salmon salad contains NO MAYO. Greek yogurt gives the same creaminess, but is low in calorie and high in protein.
Red Onion. For the right amount of bite and balance.
Cucumber. For freshness and the crunch factor. I like English or mini cucumbers because you don’t need to peel them.
Lemon. It’s citrusy brightness helps the dressing sing.
Cumin + Oregano. A surprising but sublime combo that makes the dressing a stand out.
Dill + Cilantro. Fresh herbs are the move. They make the salad taste exciting and fresh.
Feta. The creamy bits are a lovely contrast with the crunch of the cucumbers.
Sliced Almonds. Nuttiness and crunch give the salad an additional layer of flavor, texture, and satisfaction.
Currents or Raisins. My nod to the grapes in traditional Waldorf salad. They add a pleasant sweetness and yummy chewiness.
Substitution Tip!
If you don't care for currents or regular raisins, you can swap in golden raisins.
The Directions
Bake the salmon fillet in the oven.
Flake it into a large bowl.
Add the remaining salad ingredients to the bowl with the salmon.
Stir together the dressing.
Pour it over the salad.
Stir gently to combine. Taste for seasoning and ENJOY!
How to Serve Salmon Salad
As a Sandwich. Pile this salad onto your favorite bread and enjoy a scrumptious salmon salad sandwich. (Salmon salad with avocado on bread would be especially tasty!)
In Lettuce Wraps. Keep things light and healthy by serving this salad inside lettuce cups.
Over Greens. For a more traditional salad, pile this recipe on top of a bed of greens.
With Crackers. Give snack time a major upgrade by serving this salmon salad with crackers (these Ranch Crackers are my go-to).
With Grains. For a more filling meal, I love serving this salad over a bed of couscous or quinoa. (This Moroccan Couscous would be delish!)
How to Store Salmon Salad
To Store. Refrigerate salad in an airtight storage container. Three days is how long salmon salad will last in the fridge.
Meal Prep Tip
Toast the almonds up to 1 day in advance and store them at room temperature. Mix the dressing ingredients together up to 1 day in advance, and store the mixture in the refrigerator.
2mini cucumbersor ½ English cucumber, cut into 1/2-inch dice (about 1 ½ cups)
1/2cupcrumbled feta
1/4cuptoasted sliced almonds
1/4cupcurrentsraisins, or golden raisins
1/4cupchopped fresh dill
1/4cupchopped fresh cilantro
Instructions
Preheat the oven to 400 degrees F. Line a baking dish large enough to hold the salmon with a sheet of parchment paper.
Place the salmon in the pan and with paper towels, pat dry. Drizzle with the olive oil and sprinkle with ½ teaspoon cumin, ½ teaspoon salt, pepper, and ¼ teaspoon oregano. Rub to evenly coat the salmon. Bake for 14 to 18 minutes, until the salmon reaches an internal temperature of 145 degrees F on an instant read thermometer (I typically remove the salmon a few degrees early and let the carryover cooking finish the rest). The salmon should no longer be raw-looking in the center and flake easily with a fork. Let cool to room temperature.
While the salmon roasts, place the red onion in a bowl and cover with cold water. Set aside to soak (this removes some of the onion's harsh bite without losing its flavor).
Prepare the dressing: In a small mixing bowl, stir together the yogurt, lemon zest, lemon juice, and remaining ¼ teaspoon cumin, ¼ teaspoon salt, and ¼ teaspoon oregano.
Flake the salmon in chunky pieces into a large serving bowl (discard the skin).
Add the cucumber, feta, currants, dill, and cilantro.
Drain the red onion, then add it to the bowl.
Pour the dressing over the top.
Gently stir to combine. Taste and season with additional salt and pepper as desired (I add an extra pinch of each). Serve chilled or at room temperature as a wrap (or lettuce wrap), sandwich, on toast, over greens, or mixed with couscous.
Video
Notes
TO STORE: Refrigerate salad in an airtight storage container. Three days is how long salmon salad will last in the fridge.
QUANTICO, VA — The Marine Corps is modernizing and reshaping its force for the future naval expeditionary fight. Future naval warfare, specifically in the Indo-Pacific region, will require increased mobility and active communication to circumvent difficult situations. Improving battlefield communication is a major aspect of the Marine Corps' modernization efforts to meet this future fight. […]
Tulmar Safety Systems is pleased to announce that we will be participating in the Land Forces 2021 exhibition from 1-3 June, 2021 in Brisbane Australia through our Australian & New Zealand distributor, Danger Solutions. With most defence exhibitions and conferences virtual only, or canceled outright over the past 14 months due to the COVID-19 global […]
InVeris Training Solutions‘ BlueFire wireless weapons provide realism by maintaining form, fit, and function. Weapon recoil and cycling is achieved with a rechargeable magazine of compressed gas. Additionally, the weapons utilize wireless Bluetooth technology to communicate with the system, allowing the same control as FATS legacy tethered weapons but with full range of motion. There […]
For decades, Infantry Magazine was the professional journal of the grunt. Printed by the Infantry Center, it facilitated outreach to members of the branch, informed on modernization efforts and served as a platform for professional writing. This ad promoting the publication, was printed during the early 70s heyday of men’s pulp magazines, with their lurid […]
I don’t find anything particularly “happy” about Memorial Day itself. Sure, it’s a great weekend to spend kicking off summer with friends and family, but I always end up thinking about those we’ve lost in military service. Today is about sacrifice Almost every year I remind others that Memorial Day traces its roots to the […]
A business pitch is a presentation put together to entice an investor or group of investors. The goal of your pitch is to secure funding to proceed with your value proposition so you can take your idea to the market. Remember, the pitch process is about getting investors to back people; it's not about backing products and markets.
When you create your pitch, I suggest two separate formats that may be intertwined at times:
The base method, outlined in 10 points below, is an approach I developed in conjunction with Steve Zamierowski, an outstanding business plan coach at Tufts University. This template will assist you in crafting your proposal thoroughly.
The STRONG method, developed by Oren Klaff, which takes into consideration the factors of human behavior.
I have reviewed many pitch decks in my day, and I have seen both the base and the STRONG method raise real money.
There may be a few extra slides used to enhance and individualize the presentation.
This base pitch method has been used quite successfully. For example, ZwitterCo has raised millions of dollars in financing in the sustainable water pollution space, and the same is true with Anodyne NanoTech in the drug delivery biotech space. The method has secured funding for a company in the blockchain space, and I have also seen it work for industries such as food, agriculture, nutrition, biotech, services, tech, engineering, entertainment and nonprofits. I have used this format to scale a small venture/private equity fund into a large one and used it to raise money for large ventures and projects, as well.
It is industry-agnostic in that respect. Specific slides can be modified to drive home key deliverables. It doesn't matter what type of business you're starting; the key is providing milestones, deliverables, value and the financing needed to get there and ensuring investors get a return on investment.
You want to be able to show a breakeven at 24 to 36 months or significant milestones achieved that go right to a multiple of X on value. Investors know that whatever numbers you come up with, you will likely be wrong. Being upfront is essential, such as in this example: "We are asking for X amount of money now, and we know the projections that we gave may be wrong and will likely be adjusted." The same would be true for billion-dollar projects.
The second item you need to learn is to present your pitch with the weapons and tactics as explained by Klaff. You have to understand what drives human beings' behavior in sales and in a pitch situation.
Klaff explains how our brains have evolved: The old brain, or crocodile brain as he calls it, was developed millions of years ago to process fight-or-flight responses to keep us alive. The crocodile brain filters from a basic survival level: If the information is not needed, it is disregarded.
Klaff says the crocodile brain filters information in the following ways:
If it is not dangerous, ignore it.
If it is not new and exciting, ignore it.
If it is new, summarize it as quickly as possible, and forget about the details.
Do not send anything up to the neocortex for problem solving unless you have a situation that is really unexpected and out of the ordinary.
Pitches tend to originate from the neocortex of the brain — the problem solving area — but are received by the crocodile brain, which filters the importance of information. The crocodile brain looks for concrete evidence, not nuances. If you give too many details, the crocodile brain will discard or ignore your information. Your message must be simple to get through to the crocodile brain. You need an emotional story so that it's memorable. Also, you have to command attention through social status. Finally, you can't appear desperate or needy. Set the scenario so they come to you.
Klaff suggests pitching it STRONG:
Set the frame
Tell the story
Reveal the intrigue
Offer the prize
Nail the hook point
Get the deal
Once you understand how the brain works, it's time to take frame control. A frame is an instrument you use to gain power, authority, strength and control in your business communication. If your frame wins, your ideas will be accepted, but if it fails, you are at the mercy of the other person.
Pitching is about being the alpha and the leader. If you're the beta and follower, you lose. Understanding how to apply power frames is one of the most important skills you will learn in business.
The business pitch delivery
When you pitch, be dynamic. Create curiosity and desire. Make the buyers qualify themselves to do business with you. Protect your status when it comes to changing agendas, meeting times or who will attend. Understand being strong is important, and it is not about money. Your time is limited. You require respect, attention and status before anyone is going to invest in you and your ideas.
If you go to an investor or customer's office, be prompt or early. Hold the expectation that your investor or customer be on time, as well. Your time needs to be respected, and it's your responsibility to hold this boundary.
When you pitch, always finish early. If you go over, you lose. Never present for more than 20 minutes. I once reviewed a pitch from a very prestigious senior executive whose firm was considered to be iconic in the management consulting and venture industry. Everyone was afraid to tell him the truth about why he was not getting the funding. He went on for 45 slides and an hour and 10 minutes in length. I told him the truth: I lost interest, and most humans would, after the 20-minute point. He appreciated the candor and nailed his next financing trip.
QAnon-Russian Connection: Was Marjorie Taylor Greene replaced by a Russian agent? An anonymous source within the FBI has provided some astounding news regarding both QAnon and Marjorie Taylor ... Read more
Subscribe to our monthly Humor Times magazine here, available worldwide, in print or digital format. Pick up a copy at Barnes & Noble and other stores all over the U.S.
I saw a UFO with my Brother, 45 years ago, a lonely country road in Michigan, walking at night with a friend back to a lake house. (Don't ... Read more
Subscribe to our monthly Humor Times magazine here, available worldwide, in print or digital format. Pick up a copy at Barnes & Noble and other stores all over the U.S.
Maybe you got a $1,000 bonus from work or a windfall from a recently departed relative. Can you make more of it in the stock market?
It looks doable and exciting if you've been watching the stock market hit record high after record high in the last year. But is it too late? Should you be worried about the money you've already invested?
Markets occasionally get overheated or panicky. That's not a bad thing. It's what makes it possible to earn many happy returns. Ideally, you want to invest when everyone is abandoning great investments for cheap and sell them once they are priced higher than they deserve. Unfortunately, it's hard to time the market.
Most of the time, you're better off committing to systematic investing, often referred to as dollar cost average. But it's always fun to try. If you prefer a more hands-on style of investing and want to try to "beat" the market, here are four factors that might help you decide whether to put money in stocks now.
Is Now a Good Time to Invest?
This article addresses when to invest. If you know you want to invest, but aren't sure how to do it or where to do it, check out How to Invest for Beginners: The Ultimate Penny Hoarder Guide. For now though, here are four factors to consider if you are trying to answer the question: Is now a good time to invest?
1. Let's Talk About You
If you invest sensibly and stay patient, stocks are some of the best vehicles to help you become wealthier. First, though, you should make sure your money wouldn't be even better served somewhere else. Stocks returns aren't as certain as debt payments coming due, nor do they provide the comfort of cold, hard cash if something unexpected comes up.
The higher the interest rates are on credit cards or loans, the more sense it makes to pay them off before putting any money into the markets. When you pay off a credit card with a 19.99% rate, that's a sure fire way to improve your finances. Over the long haul (periods of 20 years or so), stocks tend to return between nine to 10 percent before taxes.
Some financial advisers recommend you have a rainy day fund as high as a year's worth of expenses set aside in cash before you start investing in riskier investments. Aside from helping you maintain a stable lifestyle, you'll worry less about your investments fluctuating when the market goes nutty. Whether you put aside a year's expenses or not is up to you, but it isn't prudent to put money you may need immediately into stocks.
2. Let History Guide You
Past performance of the markets doesn't guarantee anything, but it does help with perspective. Look at a long term chart for the market.
For stocks, many experienced investors prefer the S&P 500 index instead of the Dow Jones Industrial Average, because the S&P index looks at 500 stocks while the Dow only uses 30. Start with the longest time period you can on the chart settings. That might be over 50 years. Then start to look at progressively shorter periods until you feel you understand what's typical market movement and what isn't.
Now look at how the market performed during specific market events, such as when the pandemic started to ramp up in 2020 or maybe during the Great Recession in 2007 to 2009, along with the booms that followed. Eventually you'll have some perspective on how the market has performed. You can do this with individual stocks or any investment that publishes regular quotes and has a long enough history.
If the market is exceptionally high or low compared to its history, you'll want to not only understand why, but also think about whether it's higher or lower than justified. One example is how the market plunged during the pandemic. Some stocks went down by more than two thirds. Though many industries were stressed and a few companies would fail, many came roaring back.
3. Don't Pay Too Much for Profits
Wall Street calls profits "earnings." Professionals regularly compare investment prices to profitability. Let's say a share costs $10 and over the last year, the company made a dollar in profits. Then the price to earnings would be 10, since the share price is 10 times the profits made.
Investors see that as a P/E ratio. The higher the P/E ratio, the more investors are willing to pay for each dollar of profit, usually because they expect that profit to keep growing.
You can Google charts for the market's P/E ratio. In May 2021, the P/E ratio for the S&P 500 was above 40. That's the highest it's ever been for over a century, if we exclude the Great Recession, when profits plunged more dramatically than stocks. But at present, if profits for the S&P stay the same, it would take over 40 years for companies' profits to make up for the market's current price. Yikes.
Do you remember in 2006 when people were flipping houses in hours or buying way too much real estate than what they could afford? That was a sign of a classic investment bubble.
Sometimes, your friends and neighbors' comments will signal whether the market is overdone or a screaming bargain. Are they giddy about their profits? Do they act as if a rally will continue forever? Is everyone around you sharing stock tips?
That's become increasingly common in the wild market we've enjoyed for the past several years, and it's a classic signal stock prices may be due for a correction or that they will plateau.
When everyone (including the financial media) is afraid to predict that the market might go down, then there isn't much new money left to drive stock prices higher. Basically, everyone is fully invested, or at least close to it. That suggests the next piece of bad news might cause everyone to take profits at once.
Pro Tip
Don't get caught in a bubble when it pops. With enough experience and observation, you can almost feel when a market is becoming irrational.
If you're an otherwise average investor, simply reducing the impacts from a few excess markets will do wonders for your long term results. It doesn't hurt to think like a millionaire either. You can do even better if you can spot when the market has thrown the baby out with the bathwater, too and buy at those rock bottom prices alluded to earlier.
That's tougher than selling a profitable investment, because studies show we're more afraid of losing money we already have than we are about missing out on profit (even though effectively they're the same things).
And in the End
Predicting the market's direction is and always will be a challenge. You may be right on direction, but off on timing or by how much of a move the market will make.
The most you should hope for is to be more right than wrong. Even that will take experience and insight. But you can stick to a regular plan while always having an opinion. That keeps investing fun while you continue to build wealth.
Contributor Sam Levine is a Chartered Financial Analyst and a Chartered Market Technician who has written on finance topics since 2003. He is an adjunct professor of finance at Wayne State University in Michigan.
This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.
This posting includes an audio/video/photo media file: Download Now
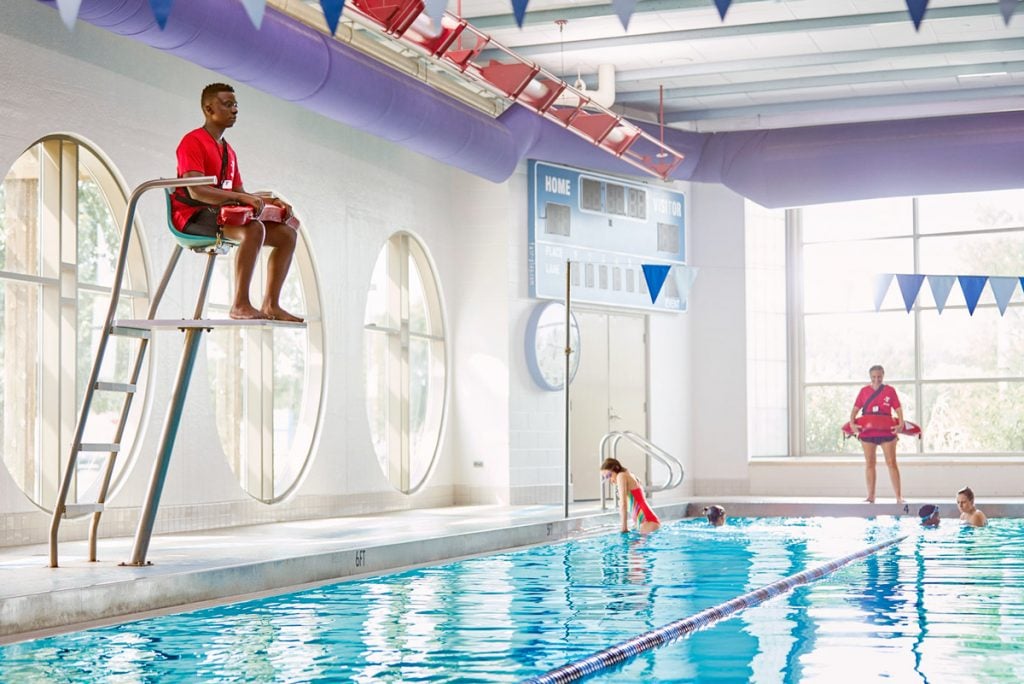
Grab your shades, sunscreen and whistle. A nationwide shortage of lifeguards has water parks, camps and municipalities scrambling to hire thousands to staff swimming pools, lakes and beaches. Some are offering free training, which takes 25 to 40 hours. Other employers are raising hourly pay to $10 to $30.
"We have raised wages at all our parks… Both lifeguard training and licence are free to each new and returning team member," said Nick Paradise, director of corporate communications for Palace Entertainment, which owns 10 water parks across the country. Hourly wages vary by location but are $15 at Sandcastle Water Park near Pittsburgh and $18 an hour at Splish Splash in Long Island, N.Y.
The shortage is largely because lifeguards have to renew their lifeguard certification every two years and thousands haven't been able to do so.
"In many parts of the country, there were long periods when people could not train, and staff and potential staff did not feel safe to train due to physical distancing guidance," said Lindsay Mondick who oversees aquatics and other initiatives for the YMCA of the U.S.A. "Now that the vaccine is more readily available to potential lifeguarding candidates, we may see a slow return."
It takes more than superior swimming skills to get a job as a lifeguard, however. Here are the requirements to become a lifeguard, the courses you'll need and what the current job market looks like.
Here's What Some Lifeguard Jobs Are Paying
Lifeguarding 2021 is no longer a minimum wage job in most cities and towns.
Job postings show employers are willing to pay more than previous summers. Check out these wages:
Happyswimmers.com in San Francisco: $22 to $30 and hour
The city of Ft. Lauderdale, Fla.: $18.93 to $29.33 an hour for waterfront lifeguards
Hyannis Harbor Hotel in Hyannis, Mass.: $25 an hour
The city of Durham, N.C.: $18 an hour
Sandcastle Water Park near Pittsburgh: $15 an hour
The city of St. Petersburg, Fla.: $13.25 to $21
Hiring Incentives for Lifeguards
Just as restaurant chains are offering cash for interviews and referrals, so are employers looking for lifeguards.
"Some of our parks are offering referral bonuses," Paradise said. "One incentive we have offered at nearly all our parks is to provide four complimentary Basic Season Passes for the team member and immediate family if they applied and completed the hiring process by a certain date."
Orange City, Iowa is paying a $20 referral bonus for a lifeguard who gets a friend to join the team at public pools. And the Parks and Recreation Department in Mesquite, Texas will pay $50 for one referral, $75 for two and $100 for three.
Mondick at the YMCA stressed that lifeguarding builds skills such as confidence, leadership and teamwork, which transfer well to any career and look great on a resume. Along with touting the crucial role lifeguards play, YMCAs across the country are trying various incentives such as referral and sign-on bonuses.
"Many YMCAs are also focused on non-traditional lifeguards, and engaging those who have retired, or those who formerly served their country in the military to now serve their community through lifeguarding positions," she added.
Here are the Basics on How To Become A Lifeguard
It takes around 25 hours of training to be certified in all lifeguard requirements. Some organizations are teaching a combination of in-person and online classes and some are all in-person courses in swimming pools.
Private training schools, non-profit groups such as the American Red Cross and the YMCA, and employers themselves offer lifeguard training classes throughout the summer.
The American Red Cross is offering a 2-day or 4-day lifeguard training course around the country immediately. Here are some of the lifeguarding course requirements.
Minimum age: 15 years
Swim 300 yards continuously
Tread water for 2 minutes using only your legs
Complete a timed mock "rescue" within 1 minute and 40 seconds by starting in the water, swimming 20 yards, making a surface dive to a depth of 7 to 10 feet, retrieving a 10-pound object, returning to the surface and swimming 20 yards on your back to return to the starting point, then exit the water without using steps or a ladder.
Applicants must also show they can do CPR on a swimmer, administer first aid and use an automated external defibrillator, also known as CPR AED.
How to Become a Waterfront Lifeguard
Waterfront lifeguarding requires additional safety training, skills and abilities. It varies by employers, but most require you to:
Swim 500 meters or 550 yards in 10 minutes or less in open waters.
Run a mile in 8 minutes and 30 seconds or less.
Master certain swimmer surveillance techniques
Use equipment such as all terrain vehicles, rescue boards, buoys, kayaks, paddleboards, masks, fins and snorkels
Know water conditions such as rip tides and how to recognize dangerous wildlife
Right now if you want to learn how to be a lifeguard, there's a good chance it might cost you nothing. For example, the Sandcastle Water Park near Pittsburgh website opens with a page touting it's raised its wages to $15 an hour and is offering free lifeguard certification. Many other employers including some YMCAs are doing the same.
If you are paying the cost varies greatly, but is well worth it. For example the city of Marion, Ohio, charges $25 for lifeguard certification courses. The American Red Cross courses range in price from $100 to $300 depending on the location.
Katherine Snow Smith is a senior writer for The Penny Hoarder.
This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.
This posting includes an audio/video/photo media file: Download Now
The weather is nice. Vaccinations are widely available. Now feels like the perfect time to go out and … spend money.
After a year of COVID-19 restrictions, the thought of returning to life as it used to be sounds wonderful. And for those who were able to keep working, cut expenses and save money during the pandemic, there's a pent-up demand to spend.
With folks so ready to leisurely stroll through the aisles of their favorite stores, dine out in restaurants, attend live events and travel again, the potential for a wave of revenge spending lurks.
What Is Revenge Spending?
Revenge spending refers to an excess in spending in an attempt to make up for putting everything on hold in 2020. It's overspending fueled by vengeance.
To make up for cancelled trips, you plan a lavish, overseas vacation. Since you had to celebrate your last birthday over Zoom, you decide to throw a catered bash at a fancy venue. The announcement to go back to the office triggers a shopping spree for a whole new wardrobe — even though you have work attire hanging in the back of your closet.
Airline travel and retail sales have seen increases in the first quarter of 2021 as restrictions drop, vaccinations roll out and stimulus checks hit bank accounts.
As nice as it is to return to some semblance of normalcy, blowing through all your savings as the result of unchecked revenge spending is not wise.
How to Prevent Revenge Spending From Derailing You Financially
First, let's make one thing clear. There's nothing wrong with treating yourself here and there — as long as you're doing it responsibly.
If you're current with all your bills, you have a solid emergency fund and you're taking care of other financial priorities like paying down debt and saving for retirement, giving into an indulgence is perfectly fine.
However, if you're struggling with excessive spending to the detriment of your financial health, here are a few things you can do.
1. Give Yourself a 7-Day Pause
When you think of something you want to buy, write it down instead of going out and purchasing it right away. If you still want that item after giving yourself a week to evaluate whether you can afford it, then you know it's not just an impulse buy.
If it's a big-ticket item, you may want to increase the time to a 30-day reflection period. As you add multiple items onto your wish list, rank them in order of what you truly want so you're not spending money on the stuff that doesn't matter as much.
Giving yourself time before you buy also will give you the opportunity to search for a better deal, which brings me to my next tip.
2. Be a Smart Shopper
Rather than splurging on something full price, try to find it for less.
Browser extensions such as Rakuten or Honey will help you find deals if you're shopping online. Cash-back apps like Ibotta or Fetch Rewards can help you save money when shopping at stores. When shopping in person, also be on the lookout for store-wide promotions or item-specific deals.
If you don't necessarily need the item to be brand new, consider second-hand stores or local buy-nothing groups.
Take advantage of credit card points when planning a vacation, and be smart about when you book your flights. If you're looking to spend money on an experience, like a spa treatment or an evening at a nice restaurant, check out deals on sites like Groupon.
Adjusting your expectations a bit may be the key to enjoying yourself post-pandemic — while staying on budget.
If you're itching for a change of scenery, consider a vacation in a city within driving distance rather than going on a cross-country trip. Pack your own groceries to take to your Airbnb so you don't have to eat out for every meal.
If you've been missing catching up with your friends in person, opt for free yoga in the park followed by a nice walk rather than paying $50 for brunch.
This list of free things to do can help you think of alternatives to do something fun without spending money.
4. Establish No-Spend Days
You don't have to shed all of the habits you picked up over the pandemic.
Challenge yourself to reserve a handful of days out of the month when you don't spend any money — outside of necessities like bills or groceries, of course.
Set your number of no-spend days so it's not overly restrictive. Because you've gone without spending during coronavirus quarantines, you may find it's not all that difficult to follow through.
This is automatically built into a 50/30/20 budget, but if you don't follow that budgeting method, it's still nice to carve out room in your budget for indulgences. That could mean setting aside money every payday to get a manicure or contributing to a sinking fund every month to save up for your next big trip.
Specifically budgeting for fun will allow you to satisfy your desires without wrecking you financially.
Rethink Your Spending Post-Pandemic
It might take some time to adjust to post-pandemic life, and that's okay.
It's also okay to come out of all that's happened over the past year and want to treat yourself to a nice getaway or a splurge that makes you feel good.
As long as you're being conscious of your spending and not making rash decisions based on a feeling of vengeance, you should be in good shape.
Nicole Dow is a senior writer at The Penny Hoarder.
This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.
This posting includes an audio/video/photo media file: Download Now
My team is taking up a collection for a joint wedding gift for a new employee in our office. She's been on staff for about a month, and our team is a mix of directors and junior-level employees (she's an entry-level staffer).
My question is: What is the appropriate amount to contribute to the collective gift? Are directors expected to give more even if they don't work directly with the recipient? We'll be giving a VISA gift card, so it's not like we have to hit a certain dollar amount for a present from the registry.
No one on staff is invited to the wedding as a guest since we don't know her well enough. I realize no one will know how much I contribute other than the person organizing the gift, but because it's a wedding I feel like I should give more than I normally would to someone I don't know well.
What's your take on this?
-D.
Dear D.,
This woman's wedding is no doubt a very big deal in her life, but let's be honest: It's not that big of a deal to you.
We all have lots of acquaintances, each of whom will celebrate big events in their lifetimes. But we only have so much money and time and brain space. So we have to focus our resources on the people we hold dearest. Office hierarchies seem irrelevant here since you don't work closely with this employee.
You're not obligated to contribute anything. But realistically speaking, there's a lot of pressure when co-workers ask for money. Since it doesn't sound like chipping in would cause you hardship, I say fork over $10 or $20.
One good practice that can help you keep gift-giving in perspective is to budget a small amount each month for gifts. Base it on how much you can afford to spend on gifts, but also on how much you want to. Keeping a separate bank account just for this budgeting category can simplify things even more.
The goal isn't just to stop yourself from spending too much on gifts. Treating the money you have to spend on other people's special occasions forces you to decide what's important to you. If you ever feel like you need to give more to someone who's a bit player in your life in honor of their special occasion, you ultimately have to accept that it may mean spending less on your best friend's birthday present or your parents' anniversary gift.
As for how to address collective gift giving in the office, I think there are a few important lessons here. First and foremost, anyone who's organizing an office gift should understand that people aren't just contributing out of goodwill. No one wants to look like the office cheapskate.
It may not seem like such a big deal if you're financially stable, but when you're living paycheck to paycheck, chipping in for random wedding gifts and birthday cakes and going-away presents throughout the year can be a real strain. Don't assume you'd know if someone you work with was struggling.
If you're the one coordinating, make it easy for anyone not to contribute without feeling ashamed. Send out an email to everyone filling them in on the plan. Make it clear that giving is completely optional. If someone doesn't give, assume there was a reason and that it's none of your business. Under no circumstances should gossip about who gave what be tolerated.
Also, tread very carefully before asking employees to contribute to someone in a higher position. Again, I don't think your respective ranks are a major factor here since you don't work directly with the bride-to-be. I also feel good about the fact that you're all going in on a gift for an entry-level employee. However, this would give me pause if entry-level employees were being asked to contribute to a gift for their boss.
Alison Green of Ask a Manager has a good rule of thumb here, which is that workplace gifts should flow downward, not upward. In other words, it's fine for managers to give their employees gifts, but employees shouldn't be asked to shell out for their boss's gift.
Individually, each of you is wondering what the appropriate amount to give is and how much everyone else is giving. But collectively, it really doesn't matter how much you give. You're showing the new co-worker that she's welcome. I'm sure she and her future spouse will appreciate the nice gesture, regardless of how big or small.
Robin Hartill is a certified financial planner and a senior writer at The Penny Hoarder. Send your tricky money questions to AskPenny@thepennyhoarder.com.
This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.
This posting includes an audio/video/photo media file: Download Now
We know your pets are part of the family, which is why it's important to make plans for pet care after death of owner.
Although it's tough to think about it, having arrangements in place will give you the peace of mind you need to ensure that your pet has the same type of loving care it has now.
There are both formal and informal arrangements you can make, each with its own benefits and drawbacks. Legally naming a pet power of attorney is one way to provide for your pets after you die. But there are others and we lay them out for you here, including what you can legally do to protect your pet.
Can I Leave Money to Spot?
The short answer is no, you can't directly leave money to your pet. The good news is that you can create a few arrangements so that your pet will be taken care of after you pass. All of these options include choosing a caregiver and leaving money with this person (or organization) in a will or trust for the purposes of caring for your pet.
The two main ways to arrange pet care after death of the owner are getting a verbal or a written arrangement. First, let's take a look at how you can choose a pet caregiver.
Choosing a Pet Caregiver
This step may be the hardest part because it can be emotional thinking about what will happen to your pet after you die. Plus, it can be a hard decision because you want to make sure you fully trust whoever will care for your pet. But you've got pet insurance in case the fur babies get sick, now you need to take that planning a step further.
If you have more than one pet, you can choose for all of them to go to one person or divided among different people. Choosing more than one person is a great option if you know that one person can't or is unwilling to take care of multiple pets.
You can name whoever you want — your aunt, best friend, co-worker or other family members. It's a good idea to choose someone who has already interacted with your pet, is a known animal lover or has cared for pets. Even if you have one person in mind pick a few backups just in case. And make sure they have agreed to the arrangement.
Again, choose carefully because this person you name will have full responsibility for your pet's care, including making major medical decisions in addition to the day-to-day stuff. You not only want to trust this person, but you want it to be someone you know will do what's best for your pet.
Something else to consider is to find a temporary caregiver in case the people you officially designate aren't available at the time of your death. For instance, your aunt happens to be on a business trip for a week, but since you named your brother as a temporary caregiver in advance, Spot will be taken care of until she returns.
What if I Can't Find a Suitable Caregiver?
It can be hard to find someone who wants to be responsible for taking care of a pet after the death of the owner. Sure, there are many organizations like the Humane Society that will take your pet. The harrowing truth is that these places may not have space to hold your pet, nor will they guarantee someone will adopt them. If you go this route, you will probably want to search out a no-skill shelter.
In response, there are organizations throughout the U.S. that ensure pet owners have a place to leave their pets when they can't care for them anymore. Keep in mind that these places will ask for a donation — think of it as money to be used for your pet. Some of these organizations include the Perpetual Pet Care Program, Pet Peace of Mind, and Peace of Mind Dog Rescue.
Make sure to do your research to ensure that you're going with a reputable organization and you know exactly how much to donate. Plus, you'll need to designate someone to care for your pet temporarily until it can be taken to the organization.
Should I Make Formal or Informal Arrangements?
The main difference between a formal and informal arrangement is that the latter is done verbally, whereas the former has an official written agreement. As in, a formal arrangement will include some form of estate planning document (we'll get to this later).
The main benefit of creating a written agreement is that you will be able to specify who will take care of your pet, including directions on how to financially care for them. You may have to pay an attorney to draft a document, or there are many free online templates available.
Informal arrangements are fine if you trust the potential caretaker and have outlined your wishes clearly. This could mean keeping in touch regularly with this person and making sure they still agree to taking care of your pet.
The downside is that the financial arrangements can get murky. You can leave money to your caretaker in your will, but you can't be absolutely sure this person will use it to care for your pet. That being said, neither option is better than the other. Make sure you're aware of what you need to do for whichever choice you make to ensure your wishes are carried out.
If you decide to create estate planning documents outlining your wishes, one of the easiest ways to do so is to create a will or a pet trust. In the will, you will name someone as the pet owner after you die and leave money to them. That way, this person will receive the money intended for your pet's care and will be the legal owner.
However, a will can't specify how the money will be used. As in, the caregiver can use the money however they wish (though it shouldn't be a huge problem if you trust them). You can create another document that outlines your wishes, though again, the caregiver is under no obligation to follow them. These instructions can include how much should go toward certain costs, or how to temporarily care for your pet if it will take time to transport them to their new home.
Disputes to your will could take weeks or longer to be resolved. In the meantime, your pet may not be with the rightful caretaker nor could there be funds to take care of them.
Consider a Pet Trust
Another estate planning document, a pet trust, is a more specific tool that formally outlines the caregiver's legal obligations to your pet. You'll name this person in the trust and provide instructions on how to care for your pet, and leave money for that very purpose. This document is set up alongside your will.
Once you pass away or become incapacitated, the pet caregiver will be named a trustee and has to follow your instructions in the pet trust. Whatever is stipulated in this document will be enacted immediately, since your assets won't go through probate or your wishes up for discussion.
Whichever type of document or arrangement you make, it's a good idea to consult a legal professional such as an estate attorney. That way, you can make an informed decision based on what's best for your beloved pet.
Contributor Sarah Li-Cain is a personal finance writer based in Jacksonville, Florida, specializing in real estate, insurance, banking, loans and credit. She is the host of the Buzzsprout and Beyond the Dollar podcasts.
This was originally published on The Penny Hoarder, which helps millions of readers worldwide earn and save money by sharing unique job opportunities, personal stories, freebies and more. The Inc. 5000 ranked The Penny Hoarder as the fastest-growing private media company in the U.S. in 2017.
This posting includes an audio/video/photo media file: Download Now